Analysis / Adoption
Why I Chose XRP: The SWIFT Payment Failure That Made Cross-Border Friction Real
My interest in XRP began with a boring accounting problem, not a price chart: an international payment that disappeared into the correspondent-banking chain and took weeks to trace.
Share this article
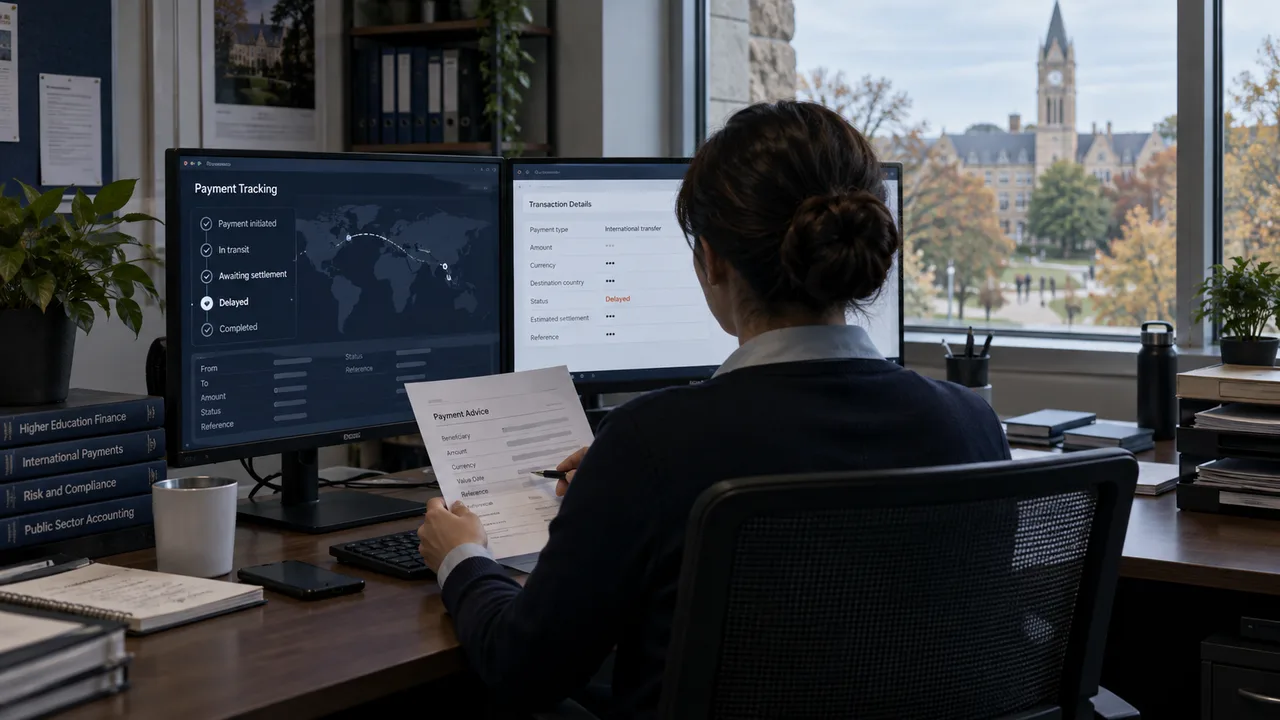
I did not become interested in XRP because of a price prediction. I became interested because I had already seen the problem it was trying to solve.
Years ago I worked for a university that regularly paid education agents in India. These were normal business payments. The agent helped recruit or support students; the university owed the agent money; our finance team sent an international payment through the banking system.
Most of the time it worked. When it did not, the experience was painful.
The payment that seemed to disappear
One particular payment never reached the recipient.
From our side, the instruction had been sent. From the agent's side, the money had not arrived. Between those two facts sat a chain of institutions, messages, settlement accounts and correspondent relationships that neither side could see clearly in real time.
The commercial problem became bigger than the accounting problem. The agent had done work and expected to be paid. Telling a business partner “the bank says we sent it” does not preserve a relationship when their account is still empty.
Eventually we paid the agent again while the original payment was being investigated. For a period, the university had effectively funded the same obligation twice. It took weeks to trace what had happened to the first payment.
That experience stayed with me because it made “cross-border payment friction” something more than a consulting phrase. It meant staff time. It meant uncertainty. It meant a supplier relationship under pressure. It meant working capital tied up while people tried to reconstruct a payment path after the fact.
SWIFT was not necessarily the villain
It is easy in crypto circles to say, “SWIFT is slow, therefore blockchain wins.” Reality is more complicated.
SWIFT is primarily a secure messaging network connecting financial institutions. The complete payment journey can also involve correspondent banks, local clearing systems, compliance checks, beneficiary banks and manual investigations. A delay that users call a “SWIFT problem” may actually occur in those other layers.
SWIFT has also improved enormously since I had that experience. The organisation now reports that a large majority of payments reach beneficiary banks very quickly, and it has built better tracking and investigation tools. SWIFT itself acknowledges, however, that exceptions and investigations remain expensive and can still take days when a payment goes wrong. Its own material describes problems such as beneficiary claims of non-receipt, returns, compliance issues and limited visibility between institutions.
That nuance matters. I am not investing on the assumption that traditional banking will stand still.
Why Ripple immediately made sense to me
When I discovered Ripple and XRP around 2018, I understood the sales pitch almost instantly.
Ripple was not trying to persuade me that international payments had a problem I had never seen. I had lived a small version of it. The idea of moving value with better end-to-end visibility and reducing the need for money to sit pre-funded around the world was economically interesting.
XRP added another layer. If a liquid digital asset could bridge two currencies quickly, perhaps institutions would not need as much capital trapped in correspondent arrangements for every corridor.
That does not mean every Ripple payment uses XRP. Ripple, the company, has offered multiple products and now supports a wider set of digital-asset and payment infrastructure. XRP is the native asset of the open-source XRP Ledger. XRPL is the network. Those three things are related, but they are not interchangeable.
I also understood that this would take years
What surprised me later was how many people expected global banking infrastructure to change like a mobile app update.
Banks are regulated. Payments touch sanctions, fraud controls, consumer protection, treasury policies, accounting, liquidity, capital rules and operational resilience. A new settlement model has to integrate with systems that may have been running for decades. Regulators and central banks need to be comfortable. Compliance teams need auditable processes. Treasury teams need liquid markets in the right currencies at the right hours.
A technology can settle in seconds and still take ten years to achieve institutional adoption.
That was part of what attracted me to Ripple. Solving the problem would require a company prepared to spend years speaking the language of banks, governments and payment providers rather than only speaking to crypto traders.
The hostility toward XRP made me more curious
Another thing caught my attention in 2018: a large part of the cryptocurrency community seemed to hate Ripple and XRP.
The criticism came from several directions. Bitcoin purists disliked the corporate association and XRP's pre-created supply. Others argued that Ripple's holdings made the ecosystem too centralised economically. Some people simply saw anything working with banks as the opposite of why cryptocurrency existed.
Rather than putting me off, that made me investigate more carefully.
I was impressed by the technical depth of people such as David Schwartz and by the fact that Ripple was led by executives who were comfortable engaging with the traditional financial system. Brad Garlinghouse did not need to persuade me that banks mattered; my own work had already shown me how embedded those institutions were.
What I could still be wrong about
This is the part every personal investment story needs.
Recognising a real problem does not tell you which company will win. Identifying a useful technology does not tell you which asset captures the economic value. A payment network can grow while its native asset underperforms. Stablecoins, tokenised deposits, CBDCs, upgraded correspondent banking and other blockchains can compete for the same use cases.
XRP also has price volatility, regulatory history, concentration questions and the usual risks of a crypto market driven partly by speculation.
Most importantly, Ripple's commercial success is not a dividend paid to XRP holders. XRP is not a Ripple share.
My original reason for buying XRP was therefore never proof of future returns. It was a thesis: the international movement of money had genuine friction; digital settlement could reduce some of it; XRPL and XRP were technically interesting attempts to solve that problem; and Ripple was unusually willing to do the slow institutional work required to bring the idea into finance.
A thesis can be sensible and still be wrong.
Related reading: The practical barriers to XRP adoption; Why liquidity matters for settlement; Ripple’s payments relationships.
XRP for Newbies
I became interested in XRP after seeing an international bank payment fail in real life. The university I worked for had to pay an overseas agent twice temporarily while banks traced the missing first payment. When I later learned about Ripple and XRP, I understood why faster and more transparent cross-border settlement could be valuable. But a real problem does not guarantee that XRP will be the winning investment.
The Bottom Line
I still think the problem that attracted me to XRP was real. Traditional cross-border payments have improved, but exceptions, liquidity and institutional coordination remain difficult. What I do not know — and nobody can know with certainty — is how much of the value created by better payments will ultimately accrue to XRP. Believing in the problem is the beginning of the investment case, not the end of it.
Sources
- SWIFT — Taking friction out of payment exceptions and investigations ↗
SWIFT · Accessed 2026-09-12
- SWIFT — Cross-border investigations could save the industry millions ↗
SWIFT · Accessed 2026-09-12
- SWIFT — Beyond borders: G20 targets and last-mile payment speed ↗
SWIFT · Accessed 2026-09-12
CONTINUE READING
Related articles
AnalysisMarkets
What Could the Japanese Yen Carry Trade Unwind Mean for XRP?
Japan's higher interest rates are making yen-funded carry trades less comfortable. An unwind could hit XRP with other risk assets first; any later benefit would depend on real payment and liquidity demand, not the existence of FX volatility alone.
AnalysisRipple
Ripple's Partners, Past and Present: What Happened to MoneyGram and Western Union?
Ripple has announced relationships with major banks and payment companies for more than a decade, but “partner” can mean anything from a pilot to a live XRP-enabled corridor. The details matter.
AnalysisAdoption
Could Companies Use XRP for Working Capital Between Countries?
XRP could shorten parts of a multinational funding cycle and reduce some idle foreign cash, but it cannot remove inventory, payroll or regulatory funding needs.