Analysis / Markets
What Could the Japanese Yen Carry Trade Unwind Mean for XRP?
Japan's higher interest rates are making yen-funded carry trades less comfortable. An unwind could hit XRP with other risk assets first; any later benefit would depend on real payment and liquidity demand, not the existence of FX volatility alone.
Share this article
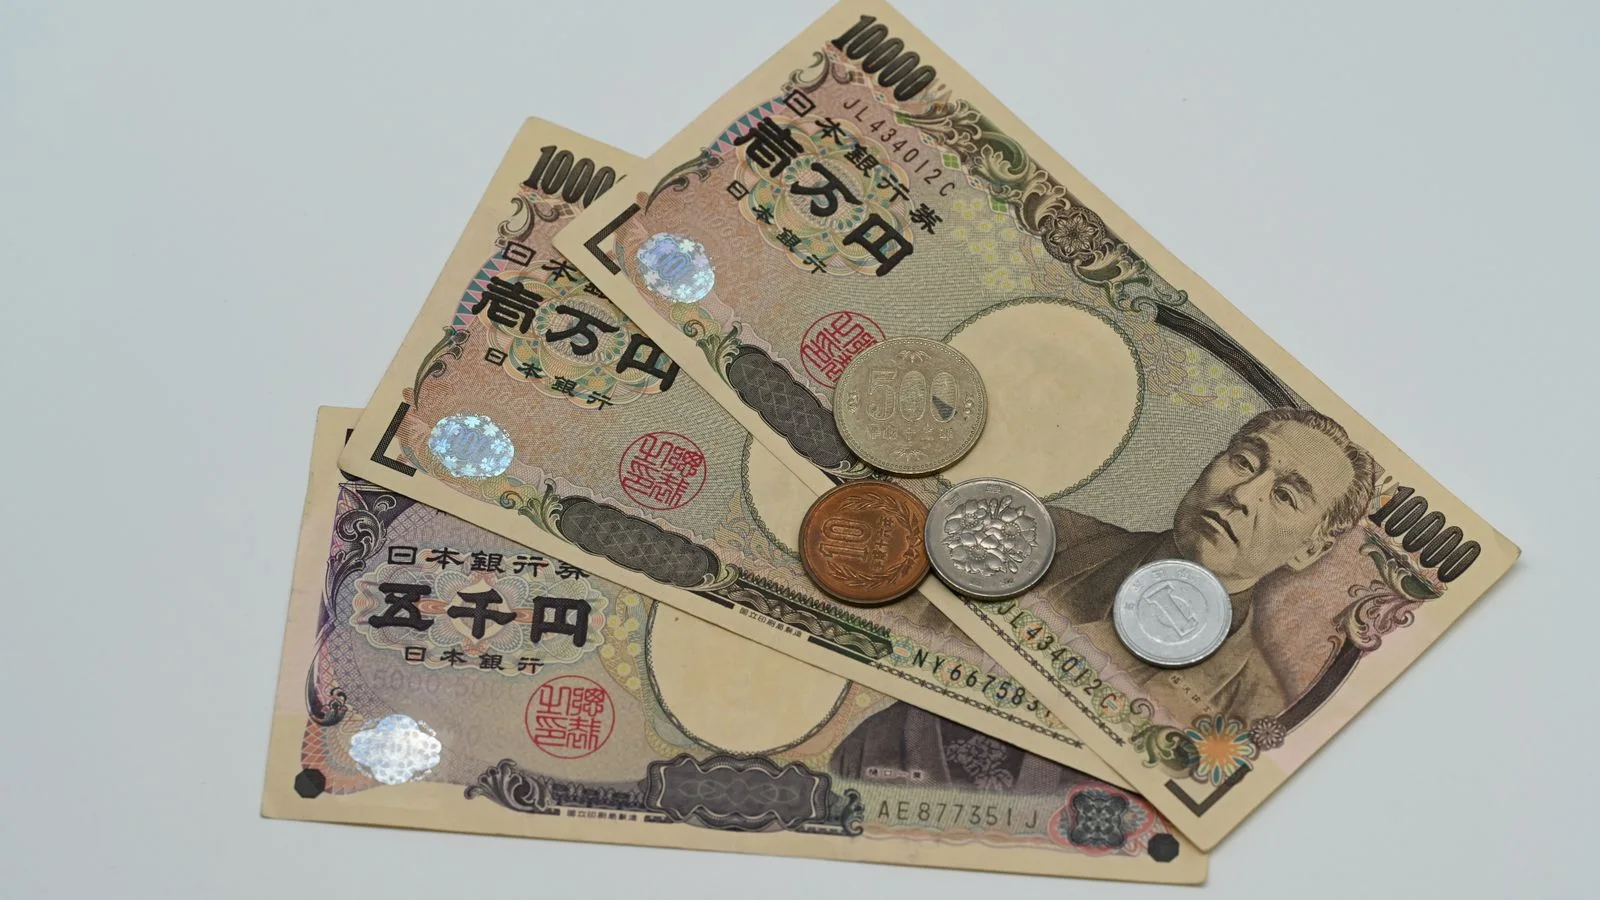
Japan has spent decades supplying the world with unusually cheap funding. That sounds like a domestic monetary-policy detail until a leveraged investor in New York, Singapore or London has borrowed yen, sold it for dollars and used the proceeds to buy technology shares, emerging-market bonds or crypto.
The Bank of Japan raised its policy rate to 1.25% in September 2026, its highest level in roughly three decades. Its 1 October summary of opinions showed policymakers debating how quickly to continue normalising policy. That has revived a practical question for XRP holders: what happens if a funding source embedded across global markets becomes more expensive or is repaid in a hurry?
The most defensible answer is not that a carry-trade unwind is automatically bullish for XRP. A rapid unwind would more likely create selling pressure across risk assets first. A later commercial opportunity for Ripple, RLUSD, the XRP Ledger or XRP itself would require a separate chain of evidence.
The Japanese yen carry trade in plain English
Assume an investor can borrow yen at 1.25% and buy a dollar asset yielding 4.25%. Ignoring transaction costs, currency moves and leverage, the apparent interest-rate spread is three percentage points. If the yen stays stable or weakens, the position may earn that spread and perhaps an additional gain on the asset.
The problem is that the loan must eventually be repaid in yen. If the yen appreciates by 8% against the dollar, the currency loss can overwhelm a 3% annual yield advantage. If the asset price is also falling, or a lender asks for more collateral, the investor may sell before the original investment thesis has time to work.
Carry trades are often built through foreign-exchange swaps and forwards rather than a simple bank loan. The economic exposure is similar: short the low-yielding funding currency and long a higher-returning asset or currency. Leverage makes the trade sensitive to small changes in funding cost, exchange rates and volatility.
Why Japan's rate path matters now
The Bank of Japan's September decision raised the policy rate to 1.25%. Its published opinions were not unanimous about the immediate pace, but several members argued that rates should continue to rise if inflation and financial conditions justify it. The next meeting is scheduled for 29–30 October 2026, so market pricing can change well before the decision itself.
The interest differential remains relevant. A US policy rate several percentage points above Japan's can still support yen-funded trades, particularly if the yen is expected to stay weak. The trade becomes less attractive when Japanese rates rise, foreign rates fall, the yen strengthens, or volatility makes the currency risk too expensive to tolerate.
No reliable source can measure the carry trade precisely. The Bank for International Settlements has explained that banking and derivatives data show yen borrowing, but not whether every borrowed yen funds a carry position. That uncertainty is a reason to treat confident claims about a single enormous number with caution.
Fact, evidence and the first XRP implication
The cleanest causal chain is straightforward:
Fact: the Bank of Japan raises rates or markets expect tighter policy.
Evidence: yen funding costs rise and the interest-rate advantage narrows.
Market mechanism: some investors reduce leveraged positions and buy yen to repay funding.
Possible XRP implication: XRP can be sold with other liquid risk assets during deleveraging.
This is not merely theoretical. The IMF's review of the August 2024 volatility episode found that a narrowing US–Japan rate differential and a stronger yen coincided with carry-trade unwinding and sharp moves across equities and currencies. The BIS also described deleveraging pressure in speculative assets including crypto.
XRP is liquid, trades continuously and is widely available on leveraged venues. Those features make it easy to sell when a portfolio manager needs cash or wants to cut risk. In the first stage of a global liquidity shock, XRP's payment narrative may matter less than its role inside a crypto risk portfolio.
Scenario A — a liquidity shock
In the bearish scenario, the yen strengthens quickly, margin requirements rise and investors sell assets to repay funding. Bitcoin falls, crypto market makers reduce inventory and XRP liquidity becomes thinner. A sell order that would normally move the market modestly then has a larger effect.
Nothing about XRPL settlement speed prevents this. The XRP Ledger can continue validating transactions normally while the market price of XRP declines. Network reliability and asset valuation are different variables.
The feedback loop can run through derivatives. Falling prices cause liquidations, liquidations create additional market sales, and exchanges demand more collateral. XRP could underperform if its derivatives market is especially leveraged, or outperform if holders are less leveraged than other crypto markets. The direction cannot be known from the carry-trade story alone.
Scenario B — FX volatility raises the value of better plumbing
Higher currency volatility creates a different business problem for a bank or corporate treasurer. A payment in transit for two days leaves more time for the exchange rate to move, more intraday exposure to manage and more uncertainty around when cash becomes available. Faster settlement can shorten that exposure window.
That is a commercial argument for better cross-border infrastructure, including Ripple Payments, stablecoins and XRPL-based settlement. It is not proof that customers will select any one provider. Banks can also improve timing through existing real-time payment links, tokenised deposits or other stablecoin networks.
Even successful adoption may not require XRP as the principal settlement asset. A USD payment may settle in RLUSD, or a tokenised bank deposit may move on XRPL while XRP is used only for a tiny network fee. As our analysis of stablecoins versus XRP explains, a stablecoin is often simpler when both parties want the same currency and trust the issuer.
Scenario C — XRP liquidity demand actually grows
The stronger XRP-specific case begins only when a real payment route uses XRP as bridge liquidity, collateral or settlement inventory. A dealer converting JPY to XRP and XRP to another currency may need working inventory. A lender financing payment providers might accept XRP collateral. A market maker may hold more XRP to quote larger two-way prices.
Those are measurable channels. Analysts should look for named corridors, repeat transaction volume, quoted market depth, inventory policies and evidence that XRP remains held for operational reasons rather than passing through momentarily.
Velocity matters. If the same XRP units can be purchased, transferred and sold many times a day, a large payment volume may be supported by a much smaller inventory. Where XRP's economic value comes from examines why high utility does not mechanically translate into the same amount of long-term holdings.
When XRPL growth would not create much XRP demand
Several plausible outcomes increase XRPL usage without materially increasing XRP demand. A bank could record tokenised deposits on the ledger while settling the legal cash leg elsewhere. An asset issuer could use Multi-Purpose Tokens for ownership records while investors transact in a stablecoin. A company could use XRP only for fees measured in tiny fractions of one XRP.
RLUSD growth can support XRPL activity but still concentrate economic demand in dollars and US government reserve assets. A payment product can also use Ripple software without using XRPL for every transaction. The correct question is not whether the brand names appear together, but which asset each transaction requires.
That is why XRPL adoption and XRP demand must be analysed through fees, reserves, liquidity, settlement inventory and investment demand separately.
What This Means for XRP
The near-term relationship is potentially negative. A disorderly yen carry-trade unwind would likely behave as a broad liquidity event, and XRP is not insulated from forced selling simply because it has a cross-border settlement use case.
The medium-term relationship is conditional. More FX volatility can strengthen the business case for faster settlement and lower prefunding, but that may benefit Ripple's software, RLUSD or XRPL tokenisation without creating meaningful XRP holdings. XRP benefits directly only where liquidity routing, collateral or settlement actually requires it.
The bullish scenario therefore has three gates: financial institutions adopt the infrastructure, their flows use XRP rather than an alternative asset, and the required inventory grows faster than transaction velocity and available market supply. Skipping any of those gates turns a macro story into a slogan.
Bottom Line
Japan's policy normalisation is a real change in global funding conditions. History shows that yen carry trades can unwind quickly and transmit volatility across stocks, bonds, currencies and crypto. XRP could fall first in that environment because liquid risk assets are sold when leverage is reduced.
A later benefit is possible, but it belongs to a different analysis. Faster settlement may be more valuable when FX markets are volatile; XRP demand rises only if actual payment, collateral or liquidity arrangements require XRP. The carry-trade unwind is therefore a risk event with a conditional infrastructure opportunity—not a guaranteed XRP catalyst.
XRP for Newbies
A carry trade is a way of borrowing where money is cheap and investing where returns look higher. For many years, investors could borrow Japanese yen at very low interest rates, exchange the yen for another currency and buy assets such as bonds or shares.
The risk is that the yen rises or Japanese borrowing costs increase. The investor may then need more dollars to repay the same yen debt, so positions can be sold quickly. XRP can fall in that kind of risk-off event even if nothing has changed on the XRP Ledger.
Sources
- Bank of Japan — Monetary Policy Meeting Schedule ↗
Bank of Japan — Monetary Policy Meeting Schedule · Accessed 2026-10-06
- Bank for International Settlements — Financial conditions in a changing global financial system ↗
Bank for International Settlements — Financial conditions in a changing global financial system · Accessed 2026-10-06
- Bank of Japan — Change in the Guideline for Money Market Operations ↗
Bank of Japan — Change in the Guideline for Money Market Operations · Accessed 2026-10-06
- Bank for International Settlements — Carry off, carry on ↗
Bank for International Settlements — Carry off, carry on · Accessed 2026-10-06
- Reuters — BOJ debated faster rate hikes in September ↗
Reuters — BOJ debated faster rate hikes in September · Accessed 2026-10-06
- International Monetary Fund — Global Financial Stability Report, October 2024, Box 1.3 ↗
International Monetary Fund — Global Financial Stability Report, October 2024, Box 1.3 · Accessed 2026-10-06
- Bank for International Settlements — Sizing up carry trades in BIS statistics ↗
Bank for International Settlements — Sizing up carry trades in BIS statistics · Accessed 2026-10-06
- Bank of Japan — Summary of Opinions, September 17–18 2026 ↗
Bank of Japan — Summary of Opinions, September 17–18 2026 · Accessed 2026-10-06
CONTINUE READING
Related articles
AnalysisXRP Ledger
XRPL's 2.8 Billion AMM Volume Spike: Why the Number Misleads
Two token-to-token pools produced 97% of one provider's seven-day XRPL AMM volume with only 185 pool-level trades. The data are real ledger activity, but the reported units have no common economic value and do not establish billions of dollars of demand.
AnalysisAdoption
Is the XRP Ledger Becoming an Institutional Blockchain? What the Data Shows
XRPL is carrying larger financial flows and more tokenised assets, but public-ledger data cannot by itself prove that banks or institutions control the activity.
AnalysisAdoption
AI Agents That Can Pay: XRPL’s Real Tools and the Controls Businesses Need
XRPL’s AI Starter Kit gives developers concrete payment tools. Explore machine purchases, XRP and RLUSD roles, and the controls separating a demo from useful commerce.