Analysis / Ripple
Ripple and Mastercard: What RLUSD Settlement Could Mean for XRP Demand
Read the November 2025 collaboration alongside Mastercard’s June 2026 developments. Separate Ripple, RLUSD, XRPL and XRP adoption before assessing demand.
Share this article
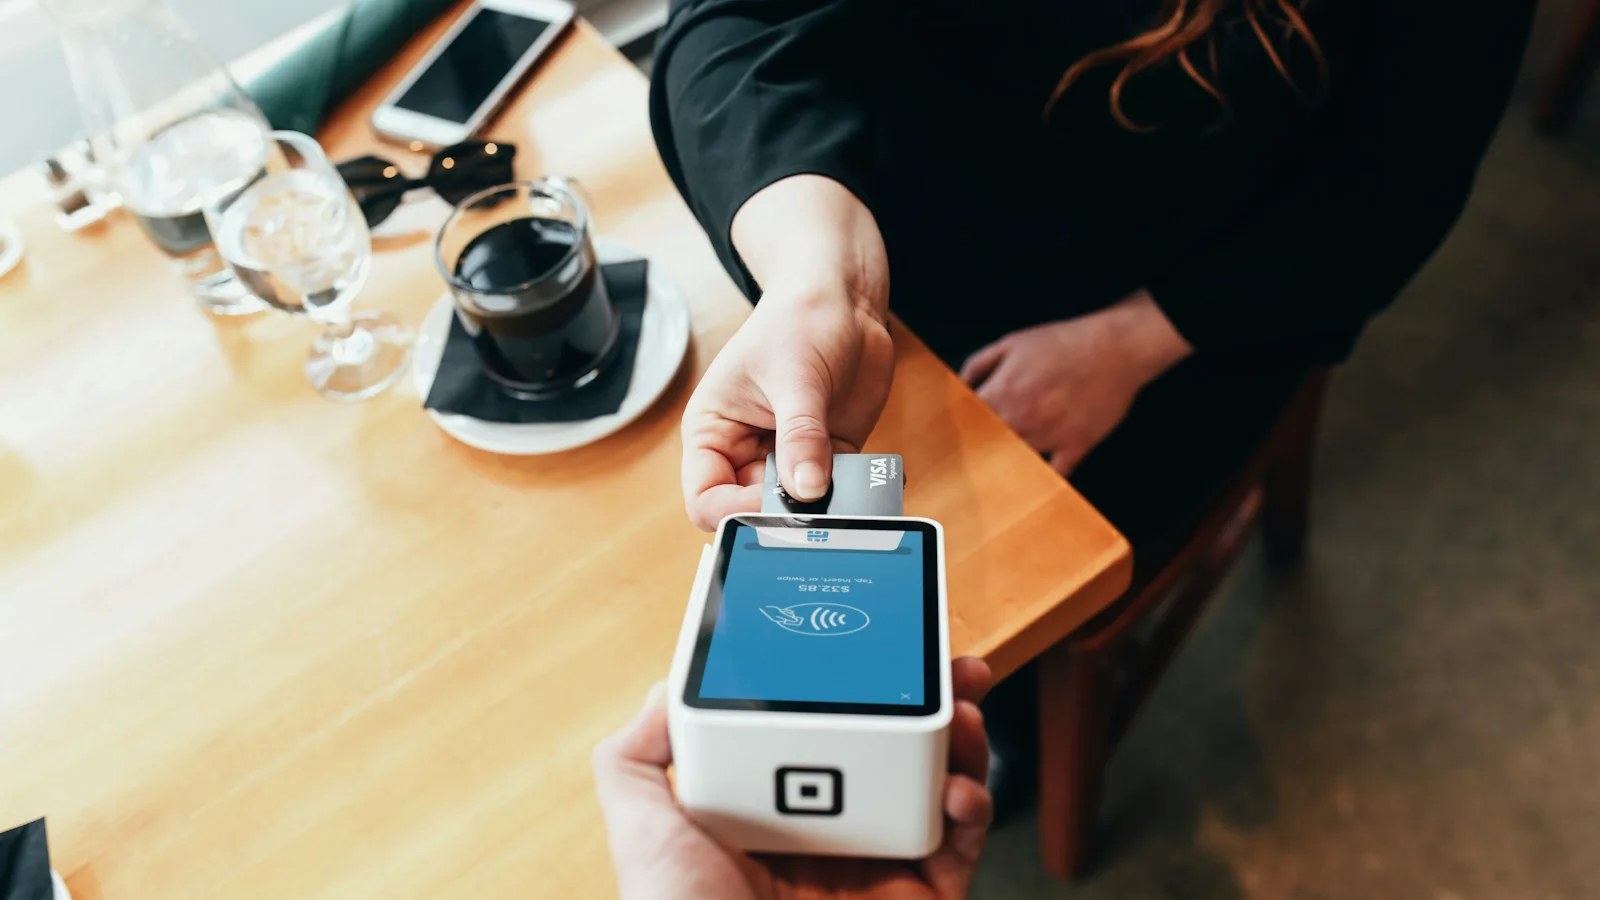
The expensive part of a card payment is not necessarily the moment a customer taps a terminal. Behind that tap sit authorisation, clearing, settlement obligations, liquidity and reconciliation. Banks can spend considerable effort moving the money that makes the familiar customer experience possible.
Ripple's relationship with Mastercard is interesting because it addresses parts of that back-office movement. The evidence now extends beyond the original November 2025 Gemini-card initiative. It still needs to be read carefully: adding a stablecoin settlement option is not the same thing as requiring every Mastercard payment to buy XRP.
Start with what was announced in 2025
Ripple's 5 November 2025 announcement described a collaboration with Mastercard, WebBank and Gemini to explore RLUSD on XRPL for settlement of fiat card transactions. WebBank is the issuer of the Gemini Credit Card. The proposed use concerned settlement between Mastercard and WebBank, rather than customers necessarily paying merchants directly in cryptocurrency.
That release used prospective language and described initial onboarding, integration planning and required regulatory approvals. It was not sufficient evidence of completed production deployment. The XRP edition of the Gemini card was a related programme, but branding and crypto rewards do not identify the asset used for institutional settlement.
The named asset was RLUSD, Ripple's dollar stablecoin, operating on the XRP Ledger. Ripple was the participating company, XRPL the proposed public ledger and XRP its native digital asset. The announcement did not specify that XRP must serve as the bridge for the principal value of those card obligations.
The June 2026 development broadens the context
Mastercard's 3 June 2026 settlement announcement says it will support regulated stablecoins including RLUSD, alongside USDC, several Paxos-issued assets and SoFiUSD. It names multiple supported networks, including XRPL, and early expected participants such as ARQ, CBW Bank, Cross River, Lead Bank and Nuvei. The plan adds choice rather than an exclusive Ripple rail.
The wording separates existing early USDC flows in selected markets from broader planned support. Its expansion builds on earlier pilots and initial live implementations, but those categories should not be assigned indiscriminately to every listed asset and participant. This article has not verified public evidence of completed RLUSD settlement volumes for the specific Gemini/WebBank programme as of 13 September 2026.
Mastercard's 10 June 2026 Agent Pay for Machines release also names Ripple among a broad group of participants and supporters. That is a separate development concerning machine-driven payments and common rules. It expands the relationship's relevance without proving that machine commerce is already routing substantial value through XRP.
What the settlement business case looks like
Imagine a bank with a dollar obligation falling due while one of its normal funding routes is constrained by operating hours. A usable stablecoin settlement option could offer another route, provided both sides can hold the asset and recognise the transfer as satisfying the obligation. Moving a token around the clock is valuable only if the surrounding agreement, controls and accounting also work.
The bank needs access to the stablecoin, a safe wallet or custodian and a redemption route. Treasury must assess counterparty exposure and hold sufficient balances without tying up excessive working capital. Reconciliation must match the transfer to the correct settlement obligation, and operations needs procedures for failed or misdirected payments. A public-ledger timestamp does not answer all of those questions.
The public releases do not disclose every detail of netting, balance requirements, conversion, redemption and commercial pricing for the Gemini/WebBank arrangement. Claims that it eliminates all prefunding or all conventional banking dependence go beyond the evidence. A dollar-backed token itself relies on reserve and issuer arrangements outside the ledger.
Four forms of adoption, four different implications
| Adoption | What it could establish | What it would not establish alone |
|---|---|---|
| Ripple services | A commercial relationship for the company | Every payment using XRP |
| RLUSD | Demand for a dollar stablecoin and its issuer arrangements | Demand for XRP as the principal settlement asset |
| XRPL | Use of the ledger and its account infrastructure | Large investment balances held in XRP |
| XRP | Actual use or holding of the native asset | A guaranteed rise in its market price |
RLUSD is not confined to XRPL; Ripple's stablecoin product information describes its availability on XRPL and Ethereum. The original card initiative explicitly selected XRPL, while the broader Mastercard announcement is multi-asset and multi-network. It would be a mistake to allocate the entire addressable Mastercard market to one chain on that basis.
Fees create some demand, but examine the arithmetic
XRPL transactions pay an XRP cost which is destroyed rather than distributed to validators. Its fee documentation identifies a typical base minimum of 10 drops, or 0.00001 XRP, for most transactions, with exceptions and higher requirements under load. That explains a direct native-asset requirement even when the transferred principal is RLUSD.
As an illustration, one million transactions each paying 0.00001 XRP would destroy 10 XRP. This is hypothetical arithmetic, not a Mastercard volume estimate or fee guarantee. Institutional settlement may also consolidate many retail transactions into fewer obligations. Card-purchase counts therefore cannot simply be multiplied by an assumed ledger fee and presented as an XRP-demand forecast.
Ledger accounts and objects can also require XRP reserves under the applicable rules. Those reserves are capacity commitments, not the same as fee burning. An institution can reuse infrastructure, so new payment volume need not create a new account for every customer purchase. Demand depends on architecture as well as volume.
Liquidity and bridge use could be more significant
The ledger's cross-currency payment model can use liquidity to deliver one asset from another. XRP could participate in routes when it offers an attractive price and depth. Direct stablecoin liquidity can also compete. Technical availability of XRP routing does not mean a bank's implementation chooses it.
XRPL AMMs add another potential liquidity channel. An XRP/RLUSD pool could require XRP inventory, but no reviewed announcement mandates such a pool for Mastercard settlement. Liquidity providers must fund inventory and manage market risk; hypothetical pools should not be counted as existing institutional holdings.
Collateral or other settlement applications could create further holding requirements if businesses actually deploy them. The useful evidence would include which asset is held, for how long, in what quantity and under what risk limits. Large gross turnover through an asset is not automatically a large permanent balance in that asset.
The XRP verdict remains conditional
The relationship is evidence that Ripple and RLUSD are relevant to serious settlement discussions and that XRPL is among the contemplated infrastructures. For XRP, it provides possible direct and indirect demand channels. The sources do not yet quantify those channels sufficiently to conclude that the relationship creates economically substantial long-term demand for the asset.
“Too early to determine the material XRP effect” is therefore the evidence-led answer. The next useful disclosures would be verified production status, settlement volumes, selected networks, liquidity routes and balances held in XRP. Those facts would tell investors more than another comparison between Mastercard's total scale and XRP's circulating supply.
XRP for Newbies
Ripple is working with Mastercard-related programmes, but the named settlement token is RLUSD, a dollar stablecoin. XRPL is one ledger option and needs some XRP for costs and reserves. That does not mean the full card-payment amount must become XRP. The relationship can help the ecosystem while its effect on XRP demand remains uncertain.
Sources
- Automated Market Makers ↗
XRPL.org · Accessed 2026-09-10
- cross-currency payment documentation ↗
cross-currency payment documentation · Accessed 2026-09-13
- 5 November 2025 announcement ↗
5 November 2025 announcement · Accessed 2026-09-13
- 10 June 2026 Agent Pay for Machines announcement ↗
10 June 2026 Agent Pay for Machines announcement · Accessed 2026-09-13
- Ripple — Ripple USD stablecoin overview ↗
Ripple — Ripple USD stablecoin overview · Accessed 2026-09-12
- 3 June 2026 settlement announcement ↗
3 June 2026 settlement announcement · Accessed 2026-09-13
- Transaction Cost ↗
XRPL.org · Accessed 2026-09-08
CONTINUE READING
Related articles
AnalysisRipple
Ripple's Partners, Past and Present: What Happened to MoneyGram and Western Union?
Ripple has announced relationships with major banks and payment companies for more than a decade, but “partner” can mean anything from a pilot to a live XRP-enabled corridor. The details matter.
NewsRipple
Ripple Targets $13 Trillion Treasury Market With RLUSD — But What Does It Mean for XRP?
Ripple sees corporate treasury management as one of the largest potential markets for its RLUSD stablecoin. Ripple Treasury customers collectively handle roughly $13 trillion in transactions each year, according to the company's stablecoin chief. The opportunity could significantly expand RLUSD usage — but the more interesting question for XRP holders is whether a successful Ripple stablecoin strengthens XRP, competes with it, or does a little of both.
AnalysisMarkets
What Could the Japanese Yen Carry Trade Unwind Mean for XRP?
Japan's higher interest rates are making yen-funded carry trades less comfortable. An unwind could hit XRP with other risk assets first; any later benefit would depend on real payment and liquidity demand, not the existence of FX volatility alone.